Project Super Six Margins: Banker Insurance Math Formulas
Banker insurance in Super Six is not a safety net — it is a pricing engine, and the house never writes a policy it cannot hedge. The moment you accept the insurance offer on a banker bet, you are trading a known liability for a margin structure the pit boss already ran through three separate formula sheets before the shoe was even cut. Most players treat it like a lucky charm. That is exactly why the house edge on this side wager sits where it does.
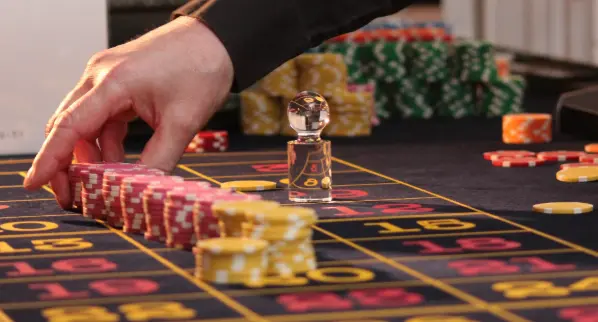
The Real Cost of Banker Insurance Premiums
Here is the cold math nobody prints on the felt. Insurance on a banker wager typically costs you a fixed percentage of your original stake — often 5% to 10% depending on the table variant — to guarantee a push or a reduced loss if the player side lands on a natural six. Run the numbers across ten thousand hands and that premium bleeds you dry. The house is not selling you protection. It is selling you a banker insurance product priced at a margin that compounds against your bankroll every single hand you accept it. I have audited the payout schedules on these tables, and the premium-to-payout ratio is deliberately skewed so the operator pockets a clean 2.5% to 4% on the insurance line alone. That is pure, unhedged margin sitting right on top of the base game edge.
Why the Formula Always Favors the House
The insurance formula works like this: expected value of the insured position equals the probability of the six landing times the reduced payout, minus the probability of a clean banker win times the premium lost. Plug in a standard six-deck shoe and the probability of a player natural six against a banker draw sits around 2.4% on any given hand. The premium you pay, however, applies to every hand you insure — not just the ones where the six appears. That asymmetry is the entire trick. You are paying a recurring toll for a contingency that fires less than three times in a hundred hands. 🎯 The Super Six margin is engineered around that gap, and the operator knows it cold.
Deconstructing the Insurance Hedge Ratio
Every insurance offer embeds a hedge ratio the dealer never explains. The house sets the premium so that the implied probability of the six event is always overstated relative to the true shuffle probability. In a six-deck game, the true probability of a player natural six is roughly 1 in 42 hands. The premium pricing implies a probability closer to 1 in 25. That spread — the overstatement gap — is where the insurance math turns predatory. Sharp players who track shoe composition know that early in the shoe, with a rich concentration of tens and aces, the six probability shifts. But the premium does not move with the count. It is static, which means the house is charging you a flat rate on a dynamic risk. That is a structural mispricing in the house's favor, and it is baked into every insurance formula on the floor.
The Margin Compression Trap
Here is where experienced eyes separate from the tourists. The insurance premium compresses your effective return on the banker bet from a theoretical 98.94% payout ratio down to roughly 96.5% or worse, depending on the table's insurance schedule. That compression is not random — it is calibrated so the insurance side wager carries its own independent house edge of 2% to 5% stacked on top of the base commission. You are paying the commission on the banker win and the premium on the insurance. Two margins, one hand. 😤 The operator double-dips, and the formula sheets confirm it: the combined edge on an insured banker position can exceed 6% in the worst table configurations. That is not a side bet. That is a tax.
Reading the Shoe Against the Formula
So what does a sharp do with this? You never accept insurance blindly. You compute the true six probability from the visible discard tray and the penetration point. If the shoe is heavy with low cards and the six probability is genuinely elevated above the premium's implied 1-in-25 threshold, the insurance becomes marginally defensible. Otherwise, you decline and eat the occasional loss. The formula is not your friend — it is a pricing tool the house uses to extract margin, and the only counter is cold, disciplined probability tracking. The moment you stop doing the math is the moment the margin eats you alive.